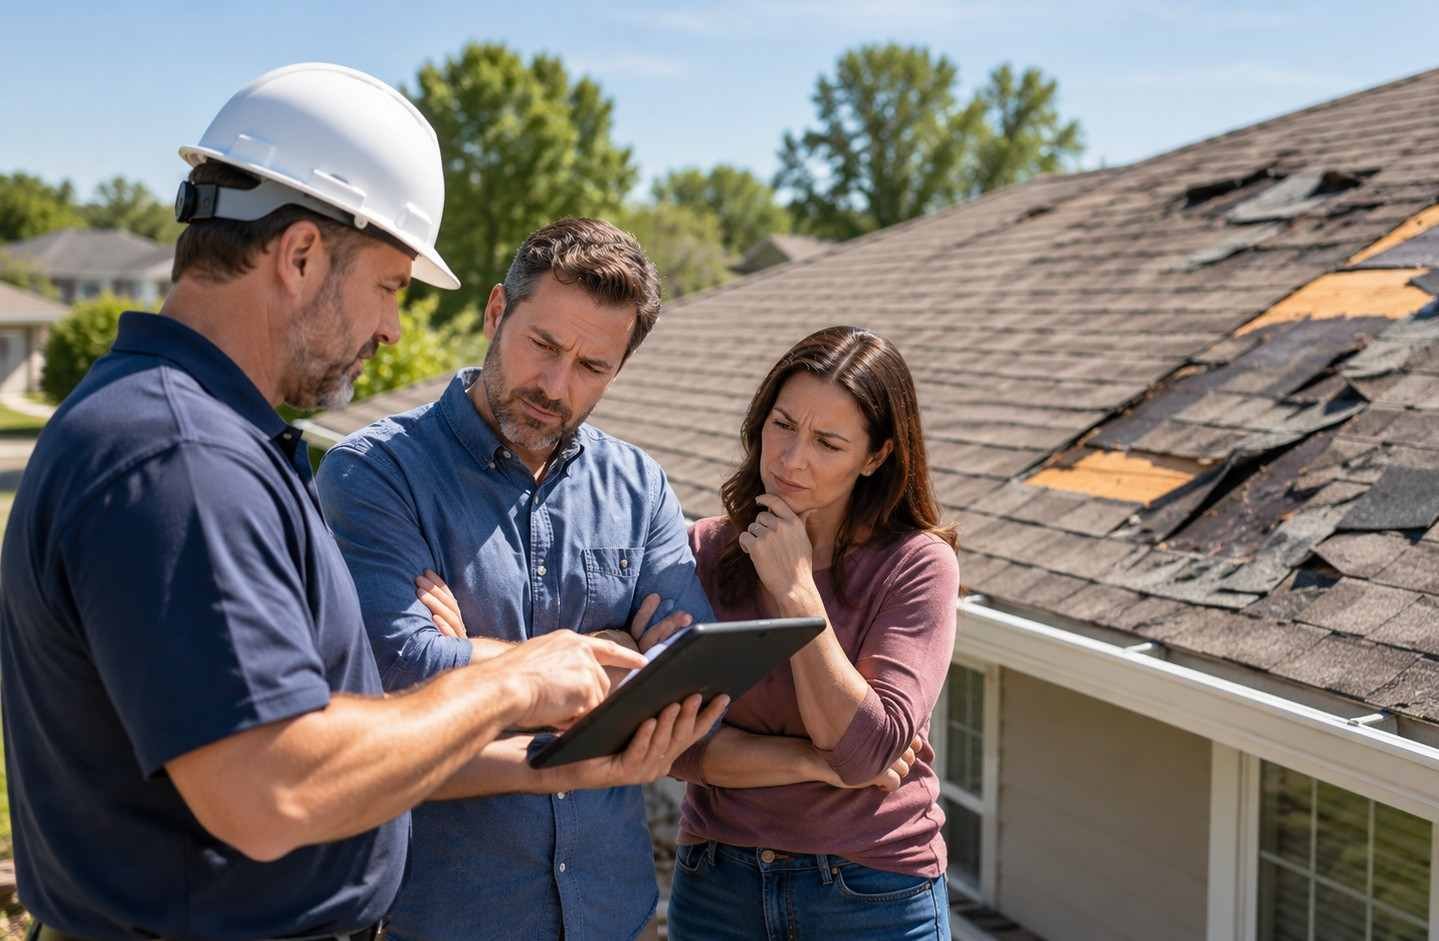
Finding missing shingles, hail marks, water stains, or storm damage can make filing an insurance claim feel like the obvious next step. I would not rush into it, though. A roof claim can involve deductibles, depreciation, inspections, policy exclusions, and documentation requirements that affect how much an insurer ultimately pays.
Understanding what to know before filing a roof insurance claim can help you decide whether filing makes sense, prepare stronger documentation, and avoid preventable mistakes. For US homeowners, the most important first step is understanding your own policy because roof coverage can differ significantly between insurers and states.
Is My Roof Damage Actually Covered by Homeowners Insurance?
Homeowners insurance generally focuses on sudden, accidental losses caused by covered events rather than routine roof maintenance.
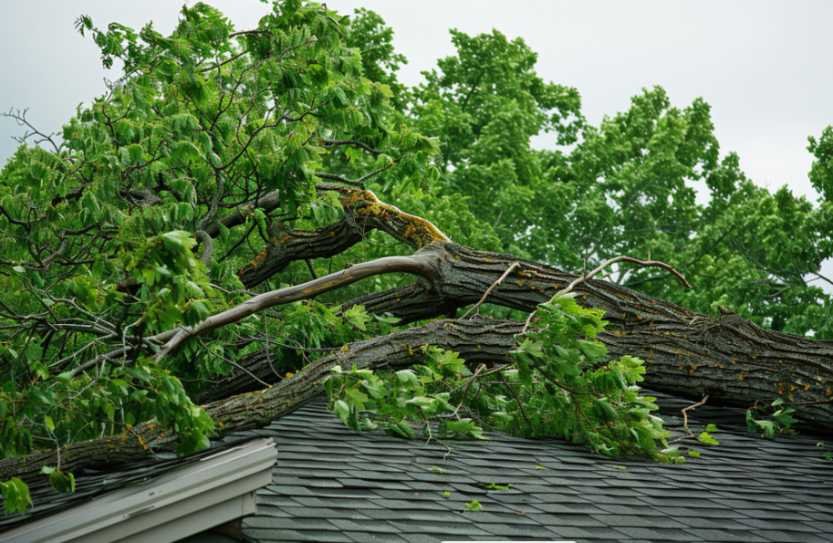
Wind, hail, fallen trees, fire, and certain other storm-related events may qualify for coverage depending on the policy. A roof damaged during a severe thunderstorm, for example, is very different from shingles that slowly deteriorated over 20 years.
Normal wear and tear, aging materials, rot, neglected leaks, poor maintenance, and installation defects are commonly excluded or limited.
That is why I would identify the probable cause of damage before assuming a roof insurance claim will pay for replacement.
Does Roof Age Affect Insurance Coverage?
Yes, roof age can affect how a claim is settled.
An older roof is not automatically uninsured, but some carriers apply different settlement terms once a roof reaches a particular age. Your policy may also use a roof payment schedule or pay actual cash value rather than full replacement cost.
Check the declarations page, endorsements, and roof-specific provisions before filing.
How Much Will Insurance Actually Pay for Roof Damage?
Two terms can dramatically affect your payout: actual cash value and replacement cost value.
ACV vs. RCV Roof Insurance
Actual cash value, or ACV, takes depreciation into account. The older and more worn the roof is, the larger the depreciation may be.
Replacement cost value, or RCV, generally pays the cost of repairing or replacing covered property with materials of similar kind and quality, subject to your policy limits, deductible, and other provisions.
With some RCV claims, the insurer initially pays the depreciated amount and releases recoverable depreciation after qualifying repairs are completed and required documentation is submitted.
Before assuming insurance will cover the full cost of a new roof, confirm which settlement method applies to your roof.
How Much Is My Roof Insurance Deductible?
Your deductible is another number I would check before opening a claim.
Some homeowners have a fixed-dollar deductible, while others may have separate percentage deductibles for wind, hail, hurricanes, or named storms. A percentage deductible is generally calculated against the home’s insured amount rather than the repair bill, which can create a much larger out-of-pocket expense.
If your roof repair estimate is close to your deductible, filing a claim may offer limited financial benefit.
Can a Roofer Waive My Insurance Deductible?
Be extremely cautious when a contractor promises a “free roof” by absorbing, rebating, or hiding your deductible.
Rules vary by state, but some states expressly prohibit these arrangements. Texas, for example, prohibits contractors from waiving, rebating, or absorbing certain property insurance deductibles.
I would never assume a deductible-waiver offer is legitimate simply because a roofer presents it as a discount. Verify your state’s law and insurance requirements before signing anything.
Should I Have My Roof Inspected Before Filing?
For non-emergency damage, I usually recommend getting a reputable roofing professional to inspect the roof before deciding whether a claim makes sense.
An inspection can identify damaged shingles, flashing, vents, gutters, impact marks, and other problems while helping you estimate the likely repair scope.
However, a roofer does not determine insurance coverage. The roofing contractor evaluates the roof; your insurer interprets your insurance contract and makes the coverage decision.
For major damage, such as a tree entering the home or active water intrusion, contact your insurer promptly while taking reasonable steps to prevent additional damage.
What Should I Document Before Filing a Roof Claim?
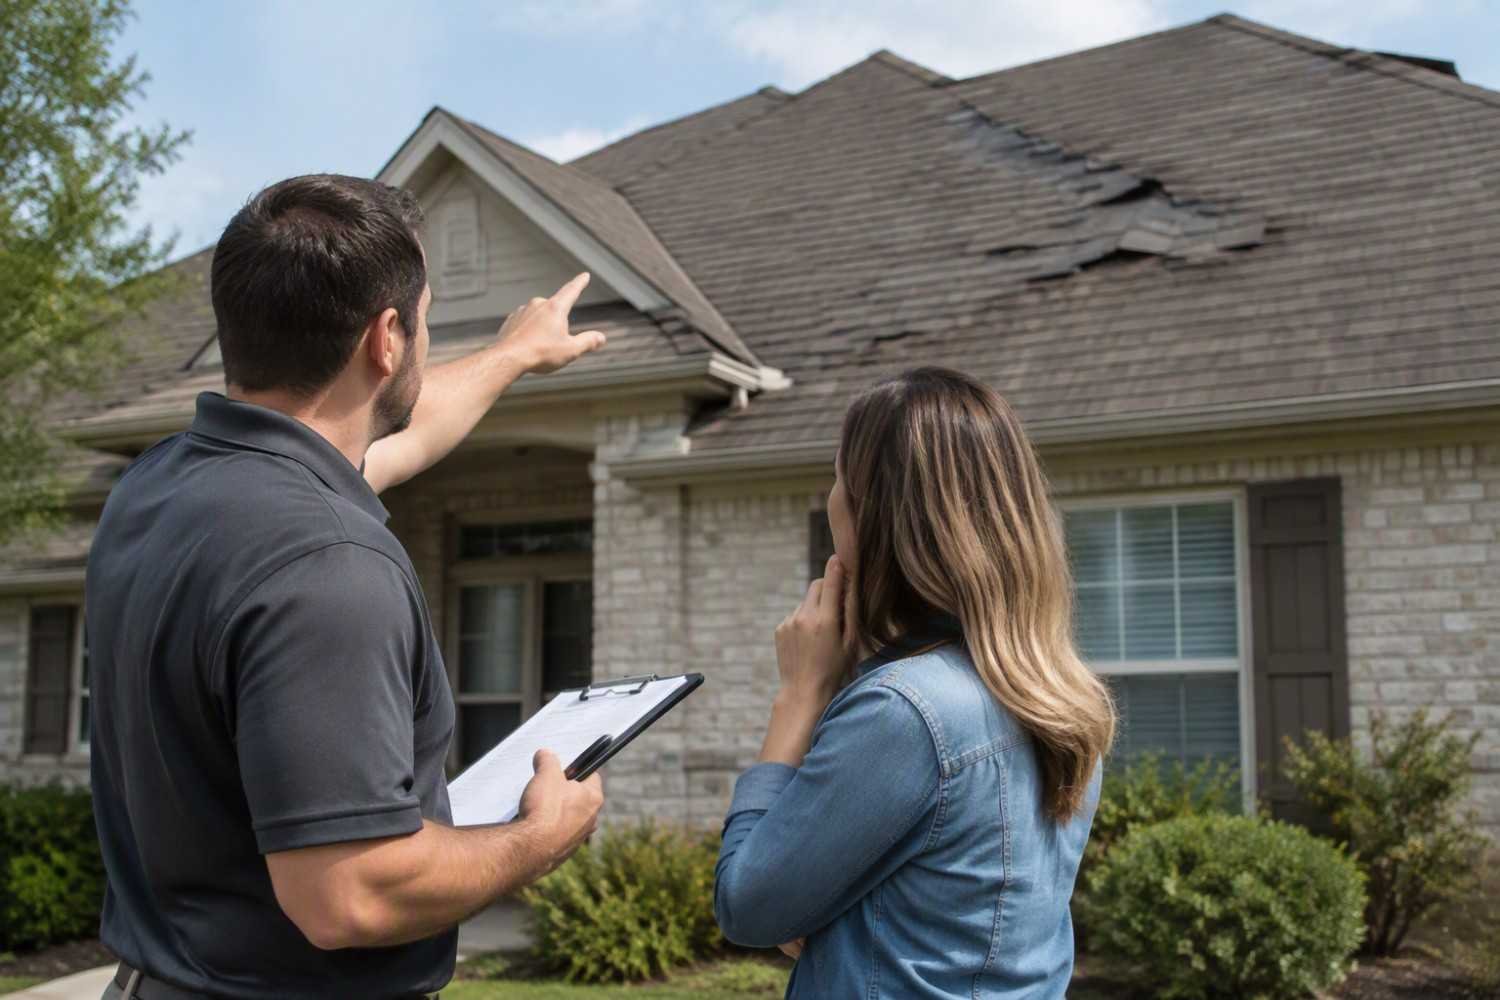
Good documentation can make the roof insurance claim process much easier.
I would photograph the overall roof and property, followed by closer images of visible damage when it is safe to do so. Document missing shingles, hail marks, damaged flashing, gutters, vents, fallen branches, ceiling stains, wet insulation, and damaged belongings.
Videos can provide additional context.
Keep the date of the storm or loss, contractor inspection reports, estimates, receipts, and communications with your insurer in one place.
Never climb onto a steep or damaged roof just to gather evidence. Let a qualified professional handle unsafe inspections.
Should I Make Temporary Roof Repairs?
Yes, when reasonably necessary to prevent additional damage.
You may need to tarp an exposed section, move belongings away from incoming water, or arrange emergency mitigation. Take photos before temporary repairs when possible and keep receipts for materials and professional services.
Avoid extensive permanent repairs before the insurer has had a reasonable opportunity to document the loss unless safety or emergency conditions require immediate work.
Can Filing a Roof Claim Affect My Insurance History?
It can.
Insurance companies may consider prior claims when making underwriting, pricing, or renewal decisions, subject to state law.
You may see advice online claiming that “three claims in five years” automatically creates a red flag. I would not treat that as a universal rule. There is no single nationwide threshold that applies to every carrier and every state.
Repeated property claims within a relatively short period can still matter, so think carefully before opening a claim solely to find out whether minor damage might be covered.
You can ask your insurer or agent how a loss inquiry or reported incident will be recorded before proceeding.
How Long Do I Have to File a Roof Insurance Claim?
Do not assume you automatically have six months, 12 months, or any other fixed period.
Policies can impose notice requirements and claim-related deadlines, while state insurance laws may affect those requirements.
I recommend checking your policy immediately after discovering storm damage and reporting a potentially covered loss within the required time.
Waiting can also make it harder to connect damage to a specific storm.
How Can I Avoid Storm Chasers and Roofing Scams?
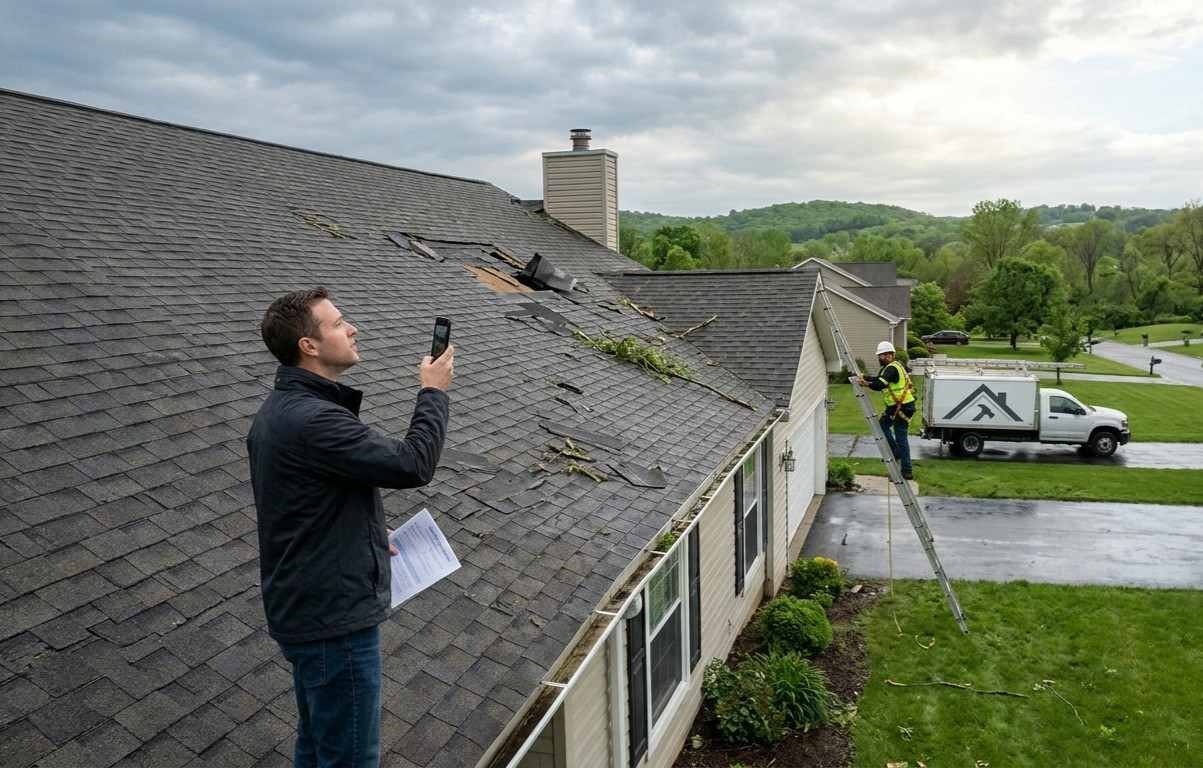
Major hailstorms and hurricanes often attract aggressive contractors looking for quick business.
Be cautious with anyone who appears immediately after a storm, pressures you into signing documents, promises guaranteed insurance approval, asks for excessive upfront payment, or offers to make your deductible disappear.
Check licensing requirements in your state, verify insurance, research local references, get written estimates, and read every contract before signing.
A reputable roofer should be comfortable explaining repair needs without guaranteeing what your insurer will pay.
What Happens After I File the Claim?
After you report the loss, the insurance company typically assigns a claim number and an adjuster.
The adjuster may inspect your roof, review photographs and estimates, evaluate the reported cause of loss, and determine which damage falls within your policy. During this stage, it can also help to understand how to evaluate roof ventilation problems, especially if moisture buildup, heat damage, or poor airflow may be contributing to the roof’s condition.
Your contractor’s estimate and the insurer’s estimate may differ because of measurements, material choices, labor rates, scope, or coverage decisions.
Read the insurer’s estimate carefully and ask questions about anything you do not understand.
Frequently Asked Questions (FAQs)
1. What should I know before filing a roof insurance claim?
The most important things to review are your coverage, deductible, roof age, ACV or RCV settlement terms, damage documentation, filing requirements, and estimated repair cost. Knowing what to know before filing a roof insurance claim can help you decide whether opening a claim makes financial sense.
2. Should I call a roofer or insurance company first?
For non-emergency damage, a professional roof inspection can help you understand the condition and repair scope. For major or actively worsening damage, notify your insurer promptly and prevent further loss.
3. Will homeowners insurance pay for an old roof?
Possibly. Coverage generally depends on what caused the damage and the policy terms rather than age alone. However, older roofs may have depreciation, ACV settlements, or roof-specific coverage limitations.
4. Can my roof insurance claim be denied?
Yes. Claims can be denied when the cause is excluded, the damage results from wear or neglect, policy requirements are not met, or the insurer determines that a covered event did not cause the loss.
Final Thoughts
When my roof has suffered storm damage, I would rather spend a little time understanding the policy than open a claim without knowing the possible financial consequences.
Learning what to know before filing a roof insurance claim means checking the cause of damage, deductible, settlement method, roof condition, documentation, deadlines, and contractor credentials before making a decision.
Every homeowners insurance policy is different. Coverage can also vary by state, insurer, roof age, and cause of loss. Prepare carefully, document everything, protect the home from additional damage, and make your filing decision based on the actual terms of your policy rather than assumptions about what insurance “should” cover.